Seed Round · SEIS/EIS · Live on iOS · Open Banking · Merchant-Funded Rewards

UK households leave £1,300 a year on the table. Wrong cards. Zero rewards on bills. We fix both.

Rewards4All connects your cards through Open Banking and tells you which card to use at each shop to earn the most. AI card optimisation plus merchant-funded cashback and bill switching, in one app. Live on the App Store. 200+ organic sign-ups. £0 marketing spend.

£1M
Raising
£10M
Post-money valuation
10%
Equity offered
200+
Organic sign-ups
✓ SEIS: 50% income tax relief App Store
09:41 · Mon 2 Jun 2026
Good morning, Alex 👋
REWARDS EARNED THIS MONTH
£84.20
↑ £32 more than last month
BEST CARD RIGHT NOW
💳
Amex Platinum Cashback
Groceries · 5% back
+£4.20
CRYPTO REWARDS
₿
Convert £12.40 → BTC
Tap to earn crypto
₿
NEARBY DEALS
🛒
Tesco, 200m away
Use Amex Gold · 4% back
4%
Live on App Store
200+ Organic Sign-ups· £0 Marketing Spend· Live on App Store· AI + Open Banking Optimisation· Live Card Optimisation· Bill Switching Cashback· SEIS/EIS Eligible· Dynamic Island Live Activities· 32M UK Card Holders· £224B UK Card Spend· FCA-Authorised Open Banking Provider· 200+ Organic Sign-ups· £0 Marketing Spend· Live on App Store· AI + Open Banking Optimisation· Live Card Optimisation· Bill Switching Cashback· SEIS/EIS Eligible· Dynamic Island Live Activities· 32M UK Card Holders· £224B UK Card Spend· FCA-Authorised Open Banking Provider·
₿ The Crypto Edge · Zero UK Competitors

The only UK platform bridging
TradFi rewards and crypto

7.4M UK adults now own crypto. None of them have a tool that connects their card rewards to crypto assets. Until now.

MARKET POSITION
We've not identified another UK product combining live card optimisation, Open Banking and merchant-funded rewards in one experience.
A clear, differentiated wedge.
🪙

Earn Crypto from Card Spend

Every transaction generates reward points. Rewards4All lets users convert those points into Bitcoin, Ethereum, or stablecoins - instantly, inside the same app.

🔗

Crypto Store Discounts

Exclusive merchant deals paid out in crypto. A new loyalty mechanism no UK bank or card issuer offers - our exclusive channel.

📊

Unified Rewards Wallet

One dashboard: cashback, Avios balances, and crypto holdings side by side. The first UK tool to unify TradFi and DeFi rewards in one view.

7.4M
UK crypto owners (FCA 2025)
£224B
Annual UK card spend
0
UK competitors with this stack
2×
Addressable market vs rewards-only
Raise Structure
£1M at £10M post-money · SEIS/EIS eligible
First £250K under SEIS (50% income tax relief) · Remaining £750K under EIS (30% relief) · HMRC advance assurance in progress
Request Data Room →

Live app. Real users. Zero paid acquisition.

Real numbers from our production database, not projections. Every metric below is measured, not estimated.

200+
Organic sign-ups
iOS App Store · £0 paid acquisition · 100% word-of-mouth
57%
Connect a card
57% of sign-ups connect at least one card - the onboarding promise lands
203
Cards added
203 reward cards added across sign-ups, measured in production
£0
Marketing spend to date
Seed capital flips this switch · paid acquisition starts immediately
What the data shows
  • Activation is real: 57% of sign-ups connect at least one card - the onboarding promise lands.
  • Organic referral loop: 88 referrals at an 18% conversion rate (viral coefficient 0.46), with zero paid acquisition.
  • Open Banking is integrated: connectivity is live through an FCA-authorised provider; user bank-linking is in final provider onboarding.
Small numbers deliberately - zero paid ads yet. The seed is to flip that switch.

Billions wasted on the wrong card swipe

UK consumers hold an average of 2.7 credit cards each. Almost none know which card earns the most at which merchant, at any given moment.

💸

£2.1 Billion Unclaimed

Cashback and rewards sitting unearned each year because UK cardholders use the wrong card at the wrong moment, or don't know their rewards expire.

£2.1B/yr
🧩

Complexity is the enemy

Reward structures differ by card, by merchant category, by month. Understanding them requires hours of research nobody has the cadence to do.

2.7 cards avg
🔍

What people do today

They guess at the till. They check TopCashback or Quidco after the fact. They use MoneySavingExpert once when applying - then never revisit. Nothing tells them which card to tap, right now, at this shop, before they pay. That's the gap.

Guess → regret

The card. The moment. The recommendation.

Rewards4All connects your cards via Open Banking, learns your spending patterns, and pushes the right card recommendation before you tap to pay.

🏦

Open Banking Integration

Open Banking, through an FCA-authorised provider, reads your real spending history across all cards. No manual entry, no guessing.

📍

Location-Aware Nudges

iOS geofencing detects when you're near Tesco, Sainsbury's, or Costa and notifies you which card earns the most before you walk in.

🤖

Toro AI - Card Intelligence

Toro is R4A's proprietary AI assistant. It maps 50+ UK cards' reward structures, bonus categories and merchant-specific rates - and answers "which card?" in natural language. Live geofencing at 120+ UK retailers fires before you pay.

⚡

Bill Switching Engine

The UK's first intelligent bill-switching tool built into a rewards app. Energy, broadband, mobile and insurance - Toro surfaces the best deal and earns cashback funded entirely from provider acquisition budgets. Zero cost to R4A.

₿

Crypto Rewards Store

Crypto card holders (Crypto.com, Coinbase, Wirex, Nexo) earn crypto on every purchase - Toro tells them where to maximise it. They then redeem earnings in our gift card store at 5% discount via Tillo + Coinbase Commerce. Closed-loop ecosystem. 7.4M UK crypto owners, zero competitors.

📊

Unified Rewards Dashboard

Retail cashback, bill switching earnings and crypto rewards in one balance view. Total lifetime earned, pending, and available to redeem - across all three income streams simultaneously.

🏝️

Dynamic Island Live Activities

Native iOS Dynamic Island integration shows live cashback balance and card recommendations without opening the app. First UK rewards app to use Apple's ActivityKit - a technical moat competitors can't replicate quickly.

📱
Live on the App Store
Free download, available now on iOS
✓ Open Banking connected
✓ 60+ UK cards mapped
✓ Geofenced nudges live
✓ Crypto rewards wallet
✓ First affiliate deals signed
✓ Dynamic Island Live Activities

Four tailwinds converging in 2026

Market conditions are working in our favour right now. Our job with the seed is to establish a credible foothold before a better-funded entrant arrives.

£224B

UK credit card spend

Annual card spend accelerating post-pandemic. Consumers are reward-conscious but have no tool to act on it in the moment.

2019

Open Banking is mature

UK pioneered Open Banking globally. APIs are stable, adoption is mainstream, and consumer trust in bank-linked apps has crossed the tipping point.

7.4M

UK crypto mainstream

7.4M UK adults own crypto (FCA 2025). Crypto is no longer niche - but no reward app bridges it with everyday card spend. We are that bridge.

50%

SEIS tax relief

50% income tax relief on first £250K. Remaining £750K under EIS at 30%. Maximum protection at earliest stage - HMRC advance assurance in progress.

TAM / SAM / SOM: a clear, winnable market

We don't need to invent behaviour. We serve UK consumers who already use credit cards for rewards but have no smart tool to maximise them.

TAM
£2.1B
Unclaimed UK credit card rewards annually
32M cardholders × £66 avg missed/yr
SAM
£380M
Digitally-active multi-card holders (25–55)
6M users × £63 addressable value
SOM (Year 3)
£4M
250K users via affiliate + premium + B2B
Conservative: 4% of SAM captured
Total UK credit card holders (TAM base)32M
Active multi-card rewards users (SAM)6M
Reachable via digital channels (SOM target)250K
Year 1 target (organic + paid)5,000
💰

Affiliate revenue per acquisition

Card issuers pay £50–£150 per successful application. We sit at the highest-intent moment in the acquisition funnel.

🔁

Recurring SaaS revenue

£2.99/month premium tier for power users: advanced analytics, unlimited card tracking, priority nudges.

🏪

Merchant-funded commission

Merchants and affiliate networks fund the rewards: we earn a share on every cashback transaction. Crypto reward conversion is a later expansion layer.

Six revenue streams, one user motion

Every time a user takes our recommendation, we monetise - via the card issuer, the merchant, a bill switch, a subscription, the crypto store, or a B2B licence. Merchants and providers pay; users earn; R4A keeps a platform margin.

Primary · Year 1

Card Issuer Referrals

£40–£120

Per approved card application. Toro recommends the right card at the moment of intent. When users apply, we earn. High intent = high conversion.

Recurring · Year 1

Premium Subscription

£49/yr

Unlimited card tracking, AI optimisation, Open Banking insights, bill switching dashboard. Predictable ARR that compounds with user growth.

Merchant · Year 1

Cashback Commission

30% of CLO

Merchants fund cashback from their marketing budgets (1–5% per transaction via AWIN/Fidel). R4A retains 30%, passes 70% to the user. Zero cashback liability on our balance sheet.

4th Stream · Year 1
⚡

Bill Switching Affiliate

Energy providers (£20–56), broadband (£25–72), mobile (£30–60) and insurance (£10–30) pay acquisition commissions via AWIN when users switch. R4A keeps 30%, user gets 70% as cashback. Confirmed UK white space - no equivalent product exists.

£60K Yr 2 ARR
5th Stream · Year 2
₿

Crypto Rewards Store

Users redeem crypto card earnings for gift cards at 5% discount (Tillo + Coinbase Commerce). R4A retains the wholesale spread. Pure product margin - no affiliate dependency, no merchant relationship required. 7.4M UK crypto owners; zero competitors.

£45K Yr 2 ARR
6th Stream · Year 3
🏢

B2B Licensing

White-label the full rewards stack for banks, employee benefits platforms and financial orgs. UK employee benefits market: £3B+. First inbound licensing enquiry already received (May 2026) before we've marketed it.

£240K+ Yr 3 ARR

How Year 1 revenue actually adds up

No hockey stick. A ramp from 0 → 5,000 MAU gives ~2,500 avg users through the year - here's the funnel against that.

AFFILIATE REVENUE
Avg MAU through Y1 (ramp 0→5K)2,500
× 10% tap a card recommendation250
× 20% apply + approved50/mo
× £75 blended commission£3,750/mo
Y1 total£45,000
Y1 exit-rate (Dec at 5K MAU)£7,500/mo = £90K run rate
PREMIUM SUBSCRIPTION
Avg MAU through Y12,500
× 3% upgrade to Premium75
× £2.99/mo£224/mo
Merchant / B2B deals (Y2+)not modelled Y1
Y1 total£2,700
Y1 exit-rate (Dec at 5K MAU)£450/mo = £5.4K run rate
Year 1 Total Revenue (Honest)
~£48K
Exiting Y1 at ~£99K annualised run rate. Year 2 is where the compounding kicks in - see projections below.

What's already in motion

Not a plan - here's what we've tested and what we'll double down on with seed capital.

Early signals · measured, not estimated
📲 iOS App Store
App is live and installable. TestFlight users converting to App Store downloads in week 1 of launch.
🗣️ Reddit + MSE forums
Early post on r/UKPersonalFinance → organic signups the same day, zero paid boost. First channel to validate intent.
🎯 Word-of-mouth
Every signup so far has come unprompted - no paid ads, no influencer deals. That's the baseline we'll scale from.
🧪 TikTok / Reels scripts
Ad creative drafted for the "First Class with Avios" narrative. First video planned for launch week.
PHASE 1: SEED (NOW–6 MONTHS)

Double down on what's already working

  • ICP: UK professionals, 25–45, holding 2+ cards, active on Reddit/MSE and travel hack forums.
  • Channel 1 - validated: r/UKPersonalFinance + MSE. Organic signups within hours of posting.
  • Channel 2 - launching: TikTok/Reels on Avios and cashback maximisation.
  • Milestone: 5,000 MAU exiting Y1, 150 premium subscribers.
PHASE 2: GROWTH (6–18 MONTHS)

Scale: Paid acquisition + affiliate revenue kicks in

  • Paid: Facebook/Instagram lookalike audiences (CAC target: £8–12)
  • Affiliate: Card issuer partnerships live. Every "Add Amex Gold" = £50–150 CPA
  • Virality: Community deal sharing drives organic referrals.
  • Target: 50,000 MAU, £1M ARR
PHASE 3: SCALE (18–36 MONTHS)

Defensible: Data network effects compound

  • B2B: Retailers pay for promoted placement in deal feed
  • International: Expand to EU markets via PSD2
  • Partnerships: White-label for neobanks (Monzo, Starling)
  • Target: 250,000 MAU, £4M ARR, EBITDA positive

Path to profitability by Year 3

Year 1 revenue reflects a realistic ramp from 0 → 5,000 MAU (~2,500 avg through the year). Assumptions: £75 blended affiliate commission, 3% free-to-paid conversion, 5% monthly churn on premium.

Metric Year 1 (2026) Year 2 (2027) Year 3 (2028)
Monthly Active Users5,00050,000250,000
Affiliate Revenue£45K£900K£3.2M
Premium Subscribers75 → 1501,5007,500
Subscription Revenue£4.5K£90K£450K
Merchant / B2B Revenue-£75K£350K
₿ Crypto Network Revenue-£40K£250K
Total Revenue~£50K£1.105M£4.25M
Y1 Exit Run Rate (Dec, annualised)£99K--
Operating Costs£480K£720K£1.4M
EBITDA−£430K+£345K+£2.6M

EBITDA Bridge: Path to Profitability

Year 1 EBITDA
-£430K
Investment phase · ramp from 0 → 5K MAU
Year 2 EBITDA
+£345K
Breakeven + growth
Year 3 EBITDA
+£2.6M
65% EBITDA margin

Operating Cost Breakdown

Cost CategoryYear 1Year 2Year 3
Engineering (2 founders)£120K£180K£350K
Cloud infrastructure (GCP)£24K£60K£120K
User acquisition (paid + organic)£200K£280K£500K
API costs (OpenAI, Open Banking)£36K£80K£180K
Legal, compliance, FCA£60K£60K£100K
Office + admin£40K£60K£150K
Total Operating Costs£480K£720K£1.4M

Zero UK competitors for this stack

The rewards market isn't empty. It's full of tools that solve the wrong part of the problem. MaxRewards (US), SaveSage (India), Kudos (US) - none operate in the UK, none have crypto.

Feature Rewards4All 🇬🇧 MaxRewards 🇺🇸 SaveSage 🇮🇳 Kudos 🇺🇸
UK market focus✓ Primary✗ US only✗ India only✗ US only
Location-based nudges✓ Offline-first~ Via Radar✗✗
Community deal sharing✓ Social feed✗✗✗
AI rewards advisor✓ Natural language✗✓ "Savvy"✗
Free to use✓ Freemium$108/yrPaid tiers✓ Free
Open Banking integration✓ Open Banking✓ Plaid✗ SMS only✓ Plaid
₿ Crypto rewards✓ Earn + store✗✗✗
Gamification / reward tiers✓ Tiers + cinema✗✗✗
Flight miles tracking✓ Fly Free goal✓✓✗

🎯 Our unfair advantage

We combine location intelligence, AI card advisory, and merchant-funded rewards in one experience. MaxRewards proved the model at $108/yr in the US. We're building the UK equivalent for 32M card holders, with crypto reward conversion as a later expansion layer.

📈 Market validation

MaxRewards has 800K+ members paying $108/yr ($86M+ ARR). SaveSage raised funding in India. The model works globally. The UK market (£224B card spend) has zero smart optimisation tools.

🚀 First-mover window

UK Open Banking is mature but no rewards app has leveraged it. Competitors would need 12+ months to build what we have. Every month of user data compounds our moat.

Why this is hard to copy

At 5K users our moat is thin, but the direction is clear: Open Banking + geofenced retailer data + user wallet patterns get stronger with every new user.

🏦 Open Banking Data Moat

The more spending data we process, the better our recommendations. Competitors starting today face 12–24 months of data catch-up.

🤝 Issuer Relationships

Affiliate partnerships with card issuers take 3–6 months to negotiate. We're building these now, creating a structural barrier for fast-followers.

📍 Behavioural Engine

Location + spending pattern + card portfolio creates a three-dimensional user model. Recommendation quality compounds with use, making switching costs high.

⚡ Speed to Market

App is live on the App Store today. Backend is production-ready on Google Cloud Run. We're 6–9 months ahead of any competitor building from scratch.

Operators with something shipped

Two founders. One live app. Working code on the App Store today.
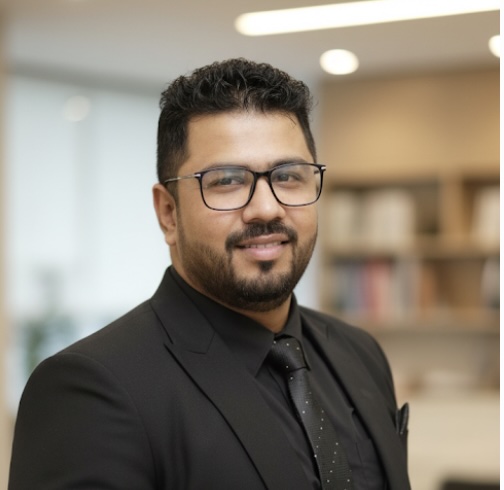
Anubhav Sood

Anubhav Sood

Co-Founder & CEO

A decade in UK fintech - product, partnerships, and affiliate economics. Why he cares: he holds 4 UK cards and has watched ~£600/yr of rewards slip past because nothing tells you what to tap at the till. Leads product, GTM, and issuer partnerships.

Shipped consumer fintech Issuer partnerships UK market
LinkedIn
SA

Dr. Sam Arora (DSc. AI)

Co-Founder & CTO

DSc. in Artificial Intelligence. Engineer who has built and operated live systems handling millions of transactions at a Fortune 100. Shipped the entire Rewards4All stack solo - iOS app, Android preview, FastAPI backend, Open Banking, and crypto integration. Why he cares: he first noticed he was losing £14 a week to the wrong card tap.

DSc. AI Shipped at scale iOS + Android Open Banking
LinkedIn

What beta users say

"

I switched to my Amex before going into Waitrose and earned more cashback in one shop than I had in the previous three months combined.

App Store user
London
"

Finally someone's built what the banks should have built years ago. I have four cards and genuinely had no idea which one to use where.

App Store user
Manchester
"

The nudge notification as I walked into Tesco was a genuinely new experience. It felt like having a financial advisor in my pocket.

App Store user
Birmingham

Simple terms. Maximum tax efficiency.

One round, one set of terms. No tranches, no ratchets, no complexity. SEIS/EIS eligible from day one.

Round Terms

Round Size£1,000,000
Post-money Valuation£10,000,000
Equity Offered10%
InstrumentOrdinary Shares
SEIS Tranche (first £250K)50% Income Tax Relief
EIS Tranche (remaining £750K)30% Income Tax Relief
Minimum Ticket£25,000
Expected CloseQ1 2027
Use of Funds: Milestone Driven
Milestone 1: Months 1–6

Launch & First 5,000 Users

40%
App Store launch Open Banking First affiliate deals User acquisition
Milestone 2: Months 7–12

Revenue & 50K Users

35%
Engineering hire Issuer partnerships Premium tier launch Growth marketing
Ongoing

Infrastructure & Legal

25%
Cloud infrastructure FCA compliance Data security Operations
WHAT THIS ROUND UNLOCKS

From live app to revenue in 12 months

📱
App Store launch
iOS + Android live with 120+ UK venues, AI advisor, community deals
🏦
Open Banking live
Open Banking. Auto-detect cards, spending analysis, smart recommendations
💷
First affiliate revenue
Card issuer partnerships generating £75+ per successful application
🚀
Series A ready
5K+ users, early revenue, cohort data in hand. If the Y1 funnel holds - £2–3M Series A at 12–18 months.

Three realistic exit paths

Rewards4All is a strategic acquisition target for banks, card issuers, crypto exchanges, and fintech comparison platforms.

🏦

Strategic Acquisition - Banks

Likely acquirers: Amex, Barclays, Chase UK, HSBC. They spend £100M+/yr acquiring new cardholders. Our app delivers pre-qualified, high-intent applicants at a fraction of their current CAC.

5–15×
Projected return multiple
₿

Crypto Exchange Acquisition

Likely acquirers: Coinbase, Crypto.com. They compete for UK crypto-curious users. Our user base - already converting card rewards to crypto - is their highest-value acquisition target.

8–20×
Projected return multiple
📊

Fintech Platform Acquisition

Likely acquirers: MoneySuperMarket (LSE: MONY, £1.2B), Experian, ClearScore. Our Open Banking-linked, spending-categorised user base is the data asset they can't build organically.

6–10×
Pre-exit Series A return

Express your interest

We're speaking with investors now. Fill in your details and we'll send you the full deck, financials, and a slot to meet the founders.

We respond within 24 hours. All information is confidential.